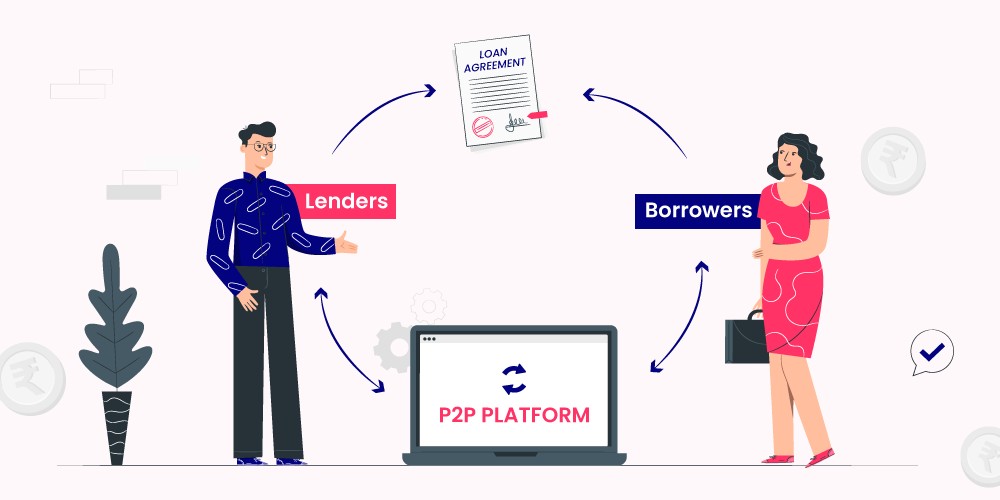
A loan lasting 30 days can carry an annual interest rate, which makes the first payout look surprisingly small to a new investor. A quoted rate of 10% does not mean earning 10% every time a monthly loan matures. The interest reflects the length of time the money is invested, and the year’s result depends on what happens between repayments.
When comparing robocash interest rates, check the loan term and payment schedule as well as the annual percentage. CrowdIndex describes an automated platform that allocates money according to portfolio settings. How much you earn over a year also depends on when principal and interest are paid and how long that money waits before being invested again.
An Annual Rate Applied to a Short Loan
Consider a hypothetical €1,000 investment earning 10% annual interest over 30 days. Using simple interest and a 365-day year, the calculation is:
€1,000 × 10% × 30 ÷ 365 = €8.22
Under those assumptions, the investor would receive €8.22 in interest if the loan repaid as agreed. A 60-day investment at the same rate would earn approximately €16.44.
These are illustrative calculations, not quoted Robocash terms. The applicable agreement determines the day-count method, when interest starts accruing, and how payments are rounded.
The distinction between annual rate and loan duration also makes comparisons easier. At the same annual rate and investment amount, a shorter loan earns less interest but is scheduled to return the principal sooner for withdrawal or possible reinvestment.
Accrued Interest and Available Cash
Interest can be recorded as accruing before it is paid. An account might show earnings increasing while the money remains unavailable for withdrawal or reinvestment.
Suppose a fictional loan accrues interest each day but pays it at maturity. After fifteen days, the account may display the interest earned so far. That amount has not necessarily reached the available cash balance.
For someone planning to withdraw income regularly, the payment schedule matters. For someone reinvesting, it determines when the earnings can start earning interest themselves. Daily accrual does not mean the interest is available to spend or reinvest.
What Reinvestment Changes
Compounding occurs when interest received becomes part of the next investment.
In a simplified example, €1,000 earning a nominal annual rate of 10%, paid and reinvested monthly at the same rate, would grow to approximately €1,104.71 after one year. Without reinvesting the interest, the earnings would be €100.
The additional €4.71 comes from earning interest on earlier interest payments. This assumes immediate reinvestment, unchanged rates, full repayment, and no fees or taxes.
An actual loan portfolio will have its own timing. Payments may arrive on different dates, and suitable investments may not be available immediately. Compounding therefore depends on the sequence of transactions, not simply on enabling an automatic setting.
The Effect of Time Between Investments
Money waiting in an account can change the result even when every funded loan pays its stated rate.
If a hypothetical €1,000 earns 10% simple annual interest for 300 days and earns nothing during the remaining 65 days, the year’s interest is approximately €82.19. That represents 8.22% of the original amount.
A portfolio might have gaps because repayments arrive before suitable loans become available. Filters for term, rate, or lender can also affect which investments qualify.
This creates a practical trade-off: more restrictive settings may better reflect an investor’s preferences, while leaving fewer opportunities for allocation. The available cash balance helps reveal how those settings are working.
When the Aim Changes to Withdrawal
Reinvestment keeps repayments moving into new positions. When an investor wants to withdraw, that same process can continue extending the time needed to collect the balance.
In a fictional portfolio with repayments scheduled over several weeks, stopping new allocations would allow cash to accumulate as those investments repay. The amount available each week would depend on actual repayments, including any delays.
A useful account report separates principal returned, interest received, money reinvested, and cash available. Those four figures explain why an account can show steady earnings while only part of its balance is ready to withdraw.